The Exchange That Nobody Funded
Jeff Yan's Hyperliquid says it took no venture money. It now settles a measurable slice of the world's perpetual futures, and the risks are unusually visible.
The sentence that distinguishes Hyperliquid from almost every other crypto company of its size appears in its own documentation, in the section on core contributors: “Development has been fully self-funded, with no VCs or external capital.” A second line repeats it, that Hyperliquid Labs “is self-funded and has not taken any external capital.” Both are the company’s own claims, not an audited fact, and they are worth treating as such. They are also, in an industry that usually announces a funding round before it announces a product, strangely quiet.
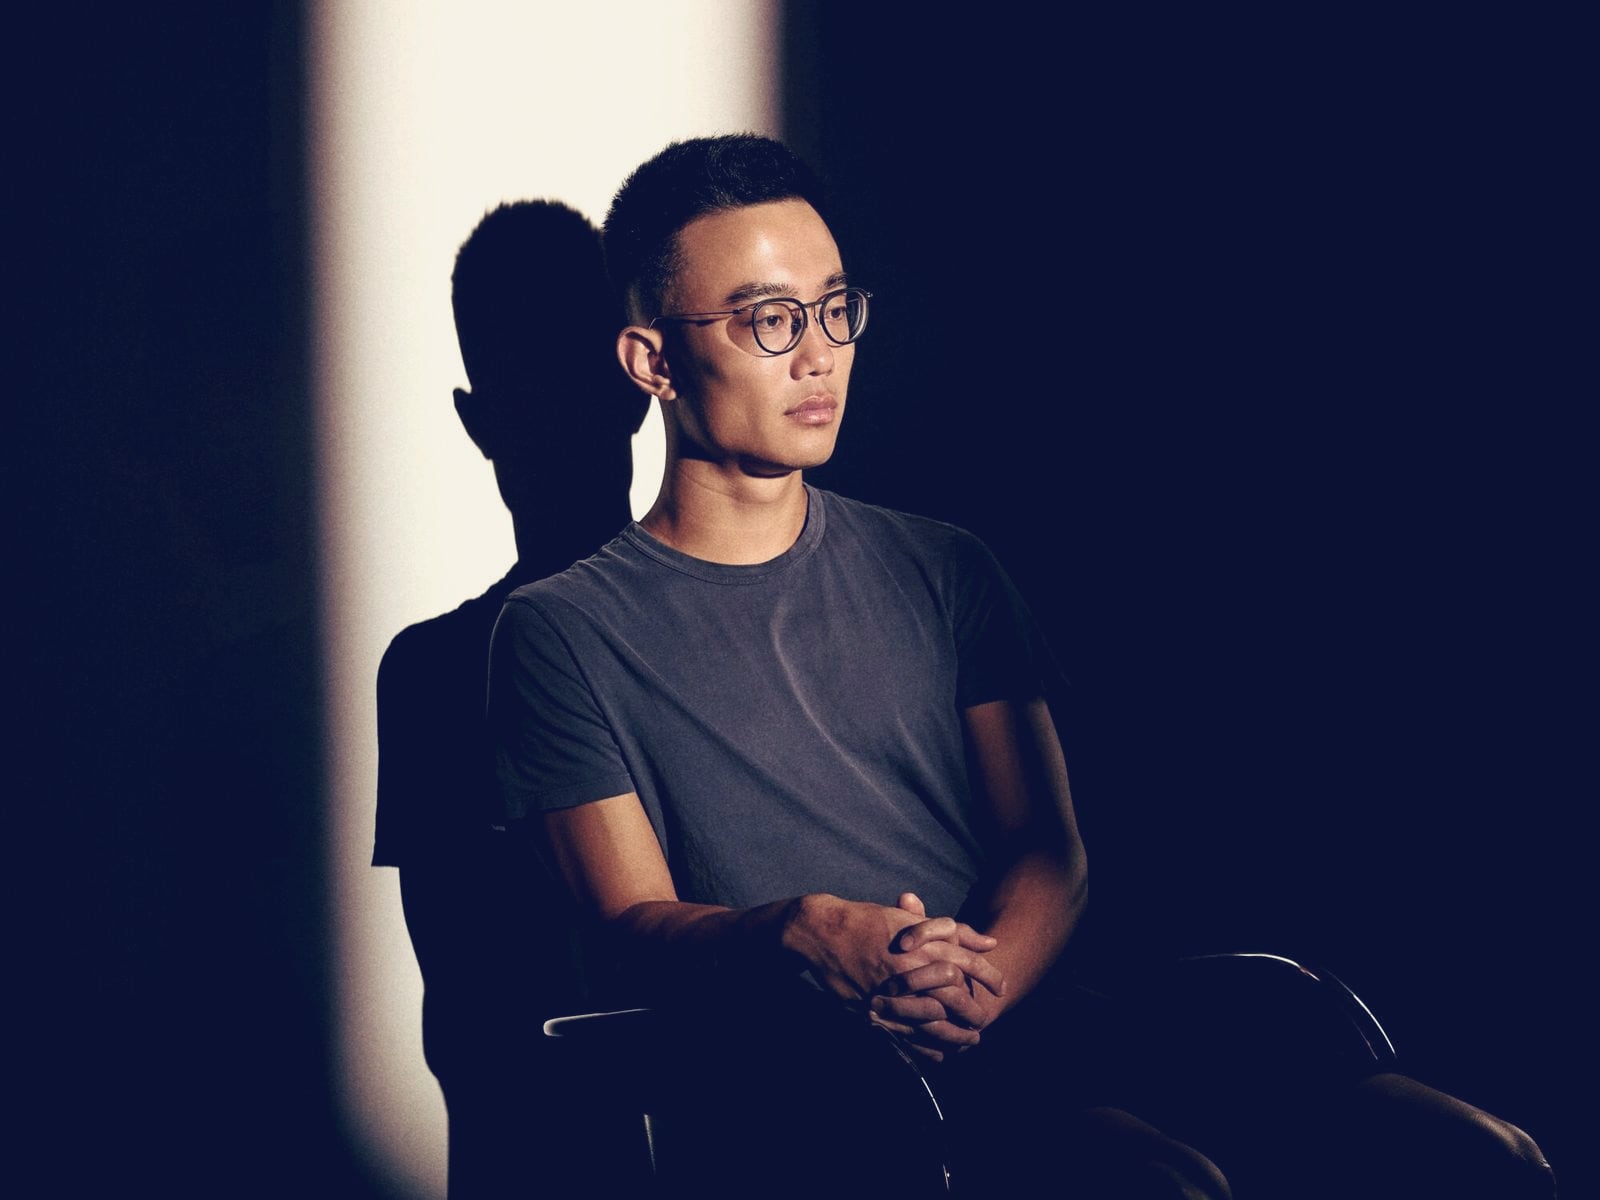
The man behind the claim is Jeff Yan, whom CoinDesk identifies as the founder of the exchange. This piece does not narrate his early life or his career before Hyperliquid, because the sources we could verify do not. What they do establish is what he built and how fast the world noticed.
A venue that a stock-exchange owner noticed
Hyperliquid is a decentralized exchange for perpetual futures, contracts with no expiry date that let traders take leveraged positions on an asset indefinitely. According to CoinDesk, it settles roughly 9 percent of all open perpetual positions worldwide. Another CoinDesk report, citing DefiLlama, put its cumulative volume above $5 trillion, with about $205 billion traded in a recent 30 days. Users trade from a wallet, with no account and no identity check.
In May 2026, Jeffrey Sprecher, chief executive of Intercontinental Exchange, which owns the New York Stock Exchange, called Hyperliquid “bigger than NASDAQ” by trading activity, and said his team had met its founders several times. CoinDesk set the HYPE token’s market value at about $15.1 billion that week, against $50 billion for Nasdaq Inc., so the comparison was about activity, not size. It also reported that Hyperliquid holds more than 70 percent of the decentralized perpetuals market. The same article quotes Sprecher on the “11 people” behind it, a figure CoinDesk tied to Hyperliquid Labs, the core development company, with a wider set of contributors and validators running the chain.
The token has had a steep ride. HYPE began trading in late November 2024 at around $3 and, by August 2025, had risen about 15-fold, to a record above $50. A month after the debut, CoinDesk reported that it had briefly topped a $10 billion market value. Hyperliquid also uses fees to buy tokens on the open market; by August 2025 the Assistance Fund’s holdings had grown from 3 million to 29.8 million HYPE. Our sources do not support a detailed account of how the token was first distributed, and we decline to supply one from memory.
What the no-VC story is evidence of
The trend is that a trading venue can now reach a scale of institutional interest while owing nothing to institutional capital. The traditional route to a market structure business ran through exchanges, brokers and regulators; this one runs through a smart contract and a user base that arrived on its own. That is a real shift. It is also one that cuts both ways, since a company with no outside investors also has no outside board, no audit committee that anyone can name, and no one obliged to ask uncomfortable questions.
It would be easy to read the absence of venture money as purity. A fairer reading is that it is a structure with strengths (fewer insiders to dump on retail) and weaknesses (fewer institutional checks). The documentation’s claim is a statement of ownership, not of safety.
The incidents
The risks are not hypothetical, and Hyperliquid’s own history supplies them.
In August 2025, the token for a stablecoin chain called Plasma had not yet launched when its futures on Hyperliquid spiked, per CoinDesk. The XPL contract rose as high as $1.80, more than 200 percent in two minutes, and open interest fell from about $160 million to $30 million as positions were auto-deleveraged. One wallet reportedly went long tens of millions of dollars and netted about $16 million. A smaller trader who said they were hedging with 1x leverage reported losing $1.4 million after the price was, in their word, “manipulated.” A market with thin pre-launch liquidity is an invitation, and a venue that lists first and asks later takes the consequences.
North Korea is the other recurrent guest. In December 2024, CoinDesk reported a record $60 million in USDC leaving the exchange in a morning, as an observer known as Tay said that North Korea-linked addresses seemed to be probing it: “DPRK doesn’t trade. DPRK tests.” In August 2026, CoinDesk said wallets linked to the Lazarus Group had sold more than $30 million in bitcoin there over three weeks. The exchange said in December 2024 that no user funds were lost.
Then there is the crowd. In September 2026, federal prosecutors charged two Robinhood engineers with trading Hyperliquid perpetuals ahead of Robinhood’s listing announcements. Hyperliquid was the venue, not the defendant. That is the point: with no identity checks at the door, a venue can be a very convenient place to commit a crime.
The centralization question
The chain is described as decentralized, but its operating structure is thin. CoinDesk notes that Hyperliquid Labs is Singapore-based, and that a Bitwise filing for a HYPE exchange-traded fund told the SEC that developers cannot compel direct on-chain users to submit to KYC, anti-money-laundering or sanctions screening. ICE’s Sprecher argued that regulators should either create a new category for perpetuals or apply existing derivatives law to such venues, and CoinDesk reported that CME Group and ICE urged U.S. officials to look closely at the platform earlier this year. A small team and a single development company carry a great deal of the system’s weight.
Luck is part of the story. The venue grew in an era of record perpetuals trading, which CoinDesk, citing CoinGecko, put above $85 trillion globally in 2025. A fall in volume, a regulatory closure or a serious exploit would change the narrative quickly. Payward, the parent of Kraken, has outlined plans to offer U.S. clients derivatives on Hyperliquid’s technology through a regulated exchange, but this would not open the existing markets to Americans.
What Yan has shown is narrow and real: that a venue without outside capital can win trader attention at scale. What remains unproven is that it can carry the obligations that come with that scale.
Not financial advice.
Sources
- Hyperliquid documentation (full text), Hyperliquid, October 27, 2026
- Payward plans to offer U.S. clients onchain perpetual futures on Hyperliquid, CoinDesk, September 16, 2026
- North Korean hackers are moving tens of millions on Hyperliquid as Trump pushes to onshore the crypto platform, CoinDesk, August 31, 2026
- ICE CEO calls Hyperliquid 'bigger than Nasdaq,' says he's met its founders, CoinDesk, May 29, 2026
- XPL Futures on Hyperliquid See $130M Wiped Out Ahead of the Plasma Token's Launch, CoinDesk, August 27, 2025
- Hyperliquid's HYPE Hits Record High Above $50 on Trading Boom, Token Buybacks, CoinDesk, August 27, 2025
- Hyperliquid sees record $60M in USDC flee as North Korea said to be probing perpetuals exchange, CoinDesk, December 23, 2024
- Two Robinhood engineers charged with insider trading using Hyperliquid perpetuals, CoinDesk, September 16, 2026
Image: Photographer not credited, via IQ.wiki, Used with credit.